How Much Life Insurance Do You Need? Term vs. Whole Life Explained
SEO Title: How Much Life Insurance Do You Need? Term vs. Whole Life Explained
Meta Description: Learn how to estimate the right amount of life insurance, compare term and whole life policies, understand eligibility, prepare documents, and apply with confidence.
Suggested Slug: /how-much-life-insurance-do-you-need-term-vs-whole-life/
Primary Keyword: how much life insurance do you need
Secondary Keywords: term vs whole life insurance, life insurance coverage amount, life insurance eligibility, life insurance application documents
Introduction
Life insurance can help protect the people who depend on your income. If you die while a policy is active, the insurer may pay a death benefit to the beneficiaries named in the policy. That money may help cover everyday living costs, a mortgage, education expenses, debts, funeral costs, or other financial obligations.
The right coverage amount is different for every household. It depends on your income, debts, savings, dependents, future goals, existing insurance, and budget. The right policy also depends on how long your family may need financial protection.
This guide explains how to estimate the amount of life insurance you may need, how term insurance compares with whole life insurance, who may qualify, which documents are commonly requested, and what to expect during the application process. It is general educational information, not personalized financial advice.
What Does Life Insurance Cover?
Life insurance is a contract between you and an insurance company. You pay premiums according to the policy terms. If the insured person dies while the policy is in force, the insurer generally pays the death benefit to the named beneficiaries, subject to the policy’s terms, exclusions, and requirements. 1
Beneficiaries may include a spouse, children, another individual, a trust, or an organization. You should review beneficiary information after major life events such as marriage, divorce, the birth of a child, or a significant change in your family circumstances.
Life insurance is usually purchased for one or more of these reasons:
- Replacing the income of a person who supports the household
- Paying a mortgage, personal loan, or other debts
- Funding children’s education or other future goals
- Covering final expenses
- Protecting a business or business partner
- Supporting a spouse, child, parent, or other financial dependent
- Providing funds for people with long-term care or special support needs
How Much Life Insurance Do You Need?
A useful starting point is to estimate the money your family would need and then subtract resources that could already help them. Avoid relying only on a simple income multiplier because household needs differ widely.
A practical coverage formula
You can use this basic framework:
Estimated coverage need = financial obligations + income replacement + future goals − existing resources
1. Add your immediate financial obligations
Begin with costs your family might need to pay after your death. Depending on your situation, these may include:
- Mortgage balance
- Credit cards and personal loans
- Car loans
- Funeral and burial expenses
- Medical bills or taxes that may remain unpaid
- Business obligations or guarantees
2. Estimate income replacement
Consider how much income your household would need to replace and for how many years. A family with young children may need support for longer than a household whose children are financially independent.
For a simple estimate, multiply the annual income that needs to be replaced by the number of years of expected support. Then adjust the figure for inflation, savings, government benefits, and the surviving household member’s income.
3. Include future goals
Add major goals that may still matter if you die. These could include:
- College or vocational education
- A down payment or mortgage support
- Childcare during a transition period
- Support for a dependent adult
- A business transfer or succession plan
4. Subtract existing resources
Subtract resources that could reasonably be available to your beneficiaries, such as:
- Savings and emergency funds
- Existing individual life insurance
- Employer-provided life insurance
- Retirement assets that may be available to the household
- Other investments or income-producing assets
Do not assume that every asset will be immediately available or that employer coverage will continue after you leave a job. Review the actual terms before counting it as a long-term solution.
Example of a simple estimate
Suppose a household estimates the following:
- Debts and final expenses: $180,000
- Income replacement need: $500,000
- Education and other future goals: $120,000
- Existing savings and insurance: $200,000
The estimated gap would be:
$180,000 + $500,000 + $120,000 − $200,000 = $600,000
This is only an example of the calculation method. It is not a recommendation that every household should purchase a $600,000 policy. A licensed insurance professional can help review assumptions, policy costs, tax considerations, and available options.
Factors That Can Change Your Coverage Amount
Your coverage needs may change when your circumstances change. Review your estimate after events such as:
- Marriage or divorce
- Birth or adoption of a child
- Home purchase or major refinancing
- Starting or selling a business
- A significant change in income
- Paying off major debt
- Retirement or a change in savings
- A change in the financial needs of a dependent
The National Association of Insurance Commissioners recommends reviewing insurance needs periodically and considering dependents, debts, taxes, savings, and other resources before buying coverage. How Much Life Insurance Do You Need?
Term vs. Whole Life Insurance: What Is the Difference?
The two main options discussed by consumers are term life insurance and permanent, cash-value insurance. Whole life insurance is one type of permanent insurance.
Term life insurance
Term life insurance provides coverage for a defined period, such as 10, 20, or 30 years. If the insured person dies during the covered term, the policy may pay the death benefit to the beneficiaries.
Term insurance is often considered when the main need is temporary income protection. For example, parents may want coverage while children are dependent, or homeowners may want protection while a mortgage is outstanding.
Potential advantages of term life insurance:
- Often lower initial premiums than permanent coverage
- Straightforward death-benefit structure
- Useful for a specific financial responsibility or time period
- May provide substantial coverage for a limited budget
Points to review before buying:
- What happens when the term ends
- Whether renewal is allowed
- How renewal premiums are calculated
- Whether the policy can be converted to permanent coverage
- Whether coverage ends at a specific age
A renewal option may allow coverage to continue even if your health changes, but the premium may increase. Always read the policy terms and ask the insurer what happens at renewal. 1
Whole life insurance
Whole life insurance is permanent insurance designed to remain in force for life as long as policy requirements are met. It generally includes a death benefit and a cash-value component. Cash value may be available during the policyholder’s lifetime, but withdrawals, loans, interest, charges, and unpaid amounts can affect the policy and the amount available to beneficiaries.
Potential advantages of whole life insurance:
- Designed for lifelong coverage
- Premium structure may be more predictable than renewable term coverage
- May build cash value according to the policy terms
- Can be considered for permanent financial needs
Points to review before buying:
- Higher premiums than many term policies
- Cash-value growth assumptions and guarantees
- Surrender charges and early-exit costs
- Policy loans and how interest affects the policy
- Whether the premium remains affordable over time
- What happens if a premium is missed
Whole life policies can be complex. Ask for a clear explanation of guaranteed values, non-guaranteed illustrations, fees, surrender values, and beneficiary impacts before signing.
Term vs. whole life comparison
| Feature | Term life insurance | Whole life insurance |
|---|---|---|
| Coverage period | A selected term | Designed to last for life if requirements are met |
| Typical premium pattern | Often lower at the beginning | Usually higher than term coverage |
| Cash value | Usually no cash-value component | Typically includes a cash-value component |
| Main use | Temporary income or debt protection | Permanent protection and other long-term planning needs |
| Important question | What happens when the term ends? | How do guarantees, fees, and cash value work? |
| Main risk to review | Renewal may cost more or may not be available indefinitely | The policy may become unaffordable or lose value if poorly managed |
Neither policy type is automatically best for everyone. The appropriate choice depends on the purpose of the coverage, the length of the need, the budget, and the policy terms.
Who May Be Eligible for Life Insurance?
Eligibility is decided by each insurer. There is no single rule that guarantees approval. Underwriting may consider information such as:
- Age
- Overall health
- Medical history
- Family medical history
- Prescription medications
- Tobacco or nicotine use
- Occupation and hobbies
- Driving history
- Residence and state availability
- Amount and type of coverage requested
A health condition does not automatically mean that you cannot obtain life insurance. It may affect the available policy types, coverage amount, premium, waiting period, or underwriting requirements. Some policies may not require a traditional medical exam, but they may have different prices, coverage limits, or eligibility rules.
Never hide medical or lifestyle information on an application. Inaccurate answers can create problems during underwriting or a future claim review.
Documents and Information You May Need
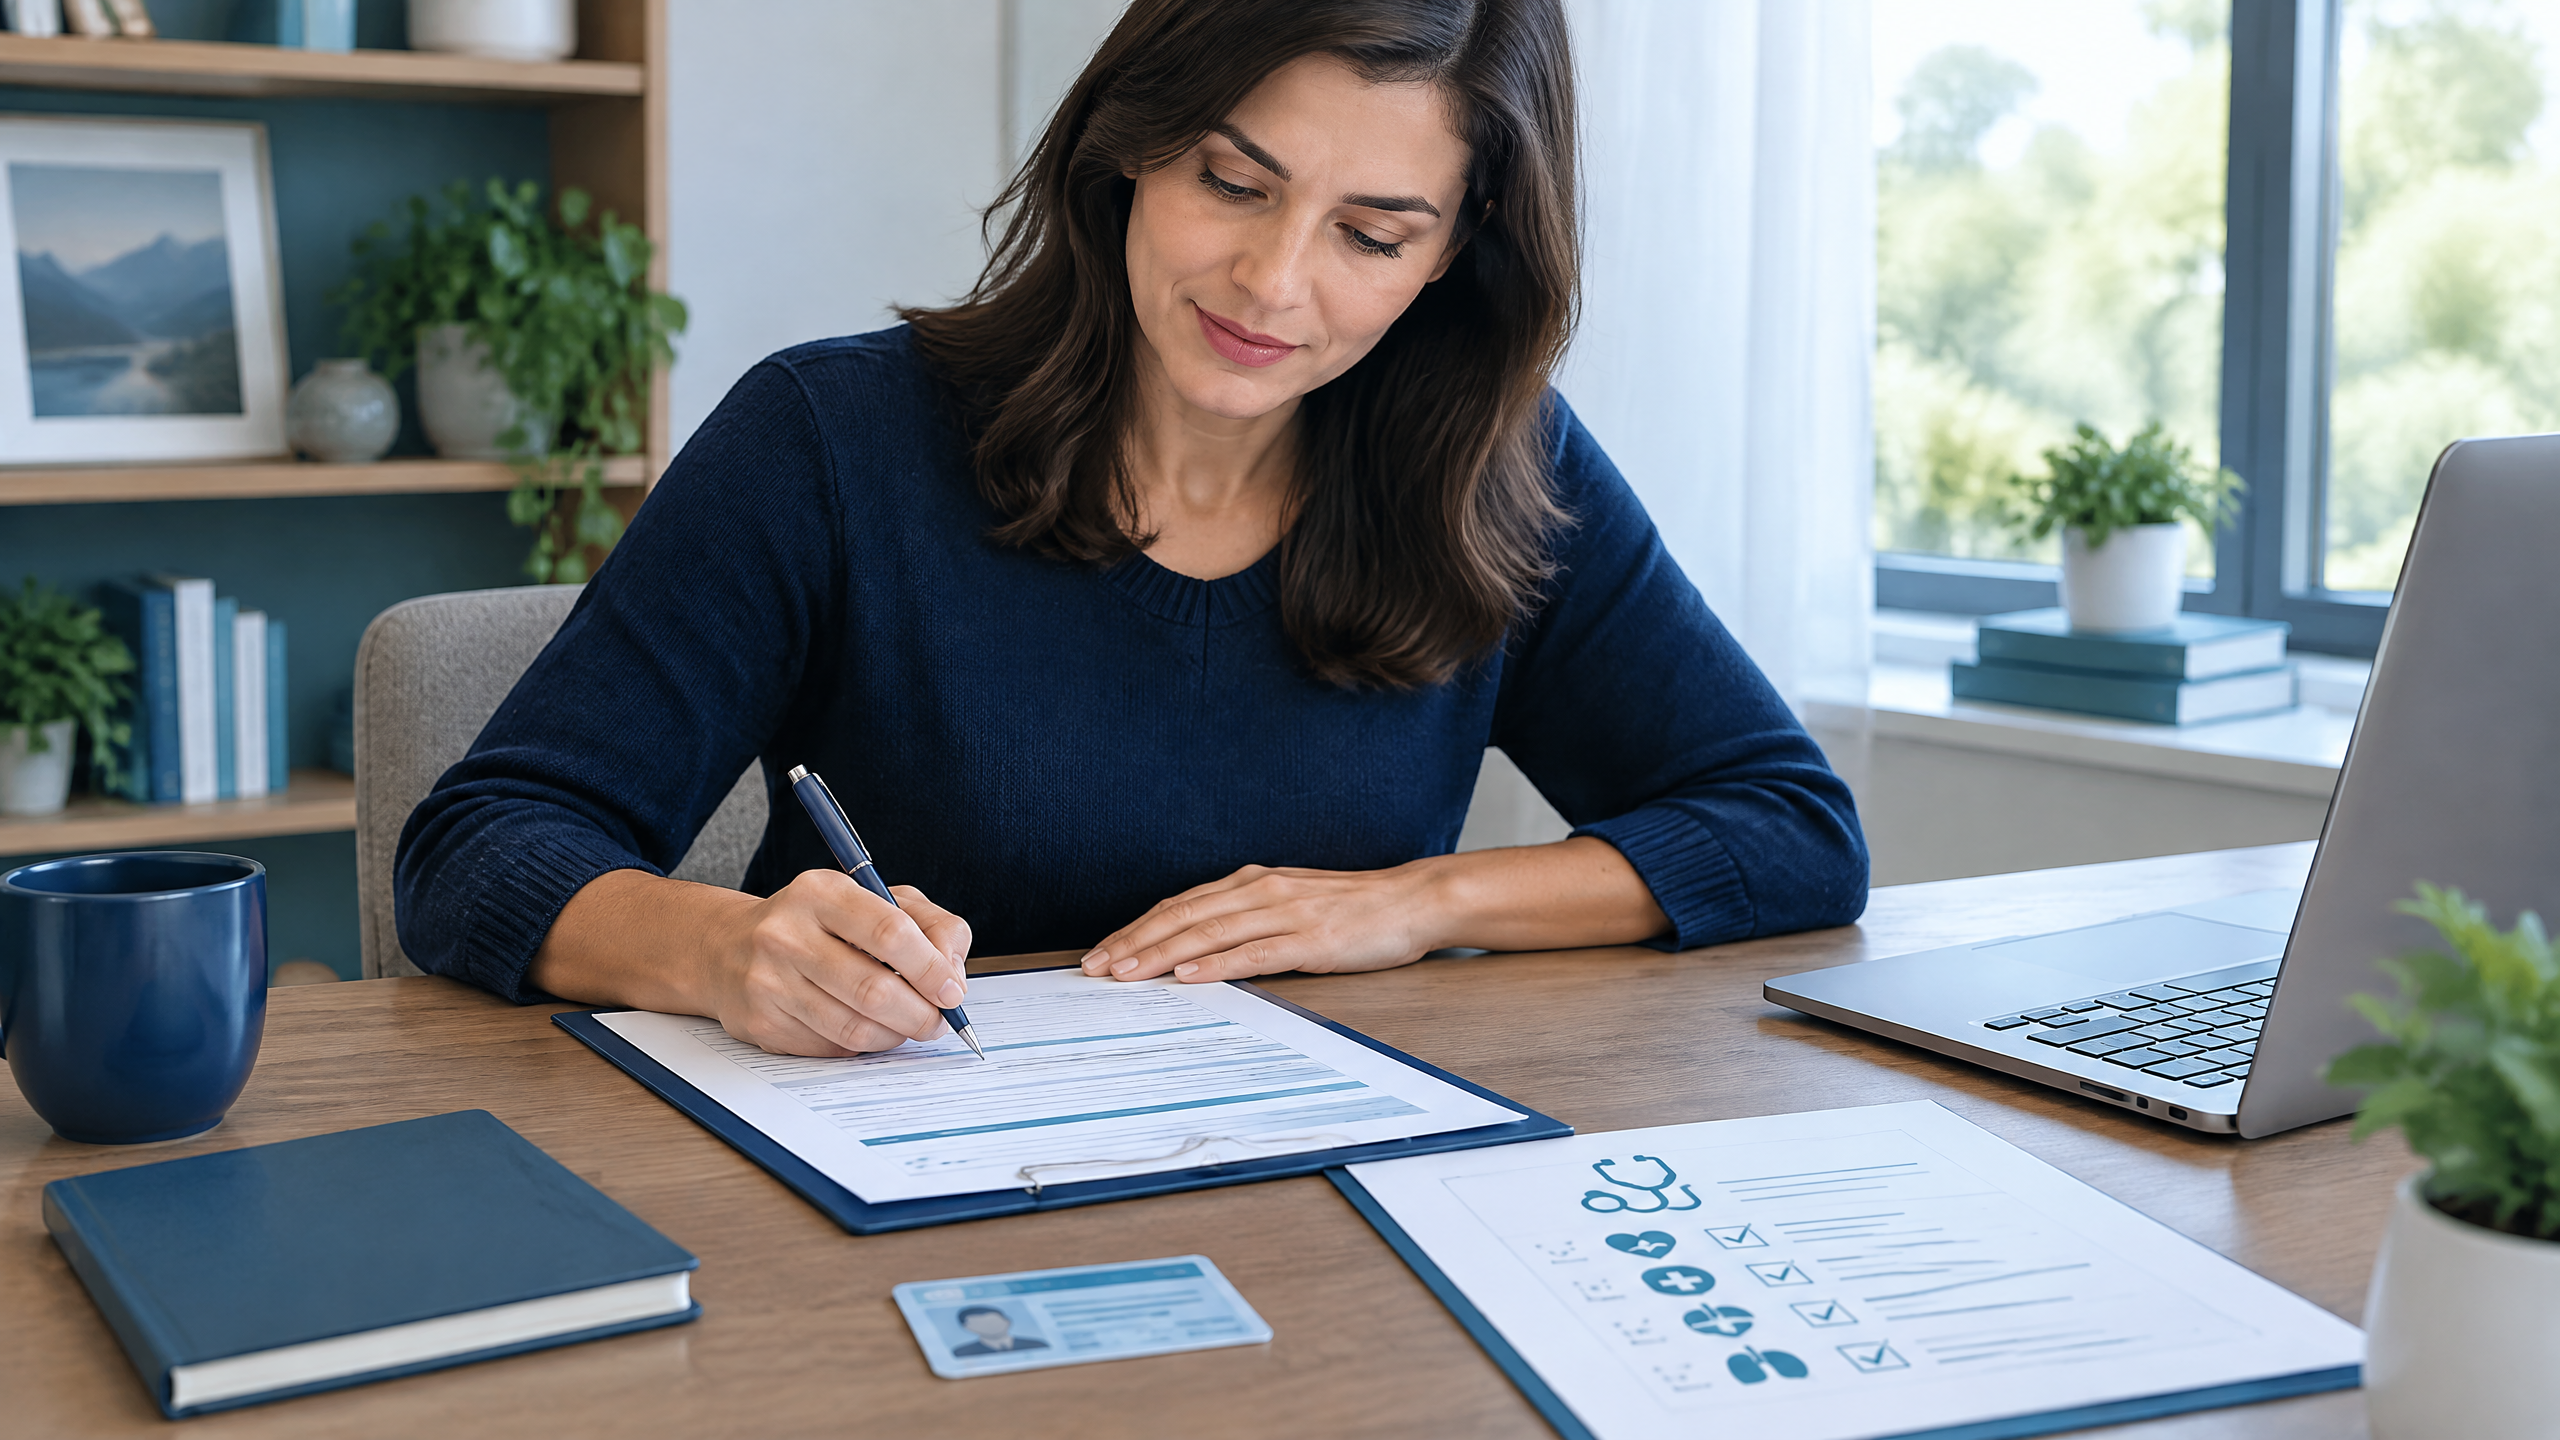
The exact requirements depend on the insurer and the policy. Prepare the following information before applying:
- Government-issued photo identification
- Social Security number or other required identification details
- Current address and contact information
- Date of birth
- Employment and income information
- Existing life insurance details
- Names and dates of birth of beneficiaries
- Personal medical history
- Family medical history
- Names and contact details for recent doctors
- List of current prescriptions and dosages
- Dates and details of surgeries or hospitalizations
- Tobacco, alcohol, and recreational substance information
- Details of dangerous hobbies or occupations
- Financial information for larger coverage requests
A medical exam may include a health questionnaire, height and weight measurements, blood pressure, pulse, and sometimes blood or urine testing. The insurer normally arranges the exam when one is required. 3
How to Apply for Life Insurance
Step 1: Define the purpose of the policy
Write down who would need financial support and what expenses the policy should address. This helps you decide whether the need is temporary, permanent, or a combination of both.
Step 2: Estimate the coverage amount
Use your debts, income replacement needs, future goals, savings, and existing coverage to estimate the financial gap. Keep your assumptions realistic and document how you reached the figure.
Step 3: Compare similar policies
Compare policies with the same coverage amount and term. Review premiums, exclusions, renewal terms, conversion options, cash-value details, riders, financial-strength information, and complaint resources.
The NAIC recommends comparing similar policies from different companies and checking whether an insurer is authorized to do business in your state. 2
Step 4: Complete the application honestly
Provide accurate personal, medical, lifestyle, and financial information. The insurer may verify answers through medical records, prescription databases, consumer reports, or other permitted sources.
Step 5: Complete underwriting requirements
The insurer may approve coverage using an application only, or it may request a phone interview, medical records, lab tests, or a medical exam. Larger policies and certain health profiles may require more information.
Step 6: Review the offer before accepting
Read the proposed policy carefully. Check the death benefit, premium, payment schedule, policy term, exclusions, riders, renewal terms, conversion options, beneficiaries, and any cash-value illustration.
Do not cancel an existing policy until replacement coverage is active and you understand the risks. Replacing a policy may involve new underwriting, new charges, a higher premium, or a loss of existing benefits.
Step 7: Keep the policy information current
Store the policy documents safely and tell a trusted beneficiary where they can be found. Review your coverage after major changes in income, debt, family responsibilities, or health-related planning.
Common Mistakes to Avoid
- Choosing a coverage amount without calculating household needs
- Buying a policy that is difficult to afford long term
- Treating employer coverage as the only protection
- Failing to review renewal premiums
- Assuming cash value grows exactly as an illustration shows
- Ignoring surrender charges and policy-loan effects
- Naming outdated beneficiaries
- Giving incomplete or inaccurate application answers
- Replacing an existing policy without comparing both contracts
- Buying a policy without understanding exclusions and guarantees
Frequently Asked Questions
Is there a standard rule for how much life insurance I need?
There is no universal amount that fits every household. A useful estimate considers debts, income replacement, future goals, final expenses, savings, and existing coverage. Your result should be reviewed against your budget and the actual policy terms.
Is term life insurance cheaper than whole life insurance?
Term life insurance often has lower initial premiums because it provides coverage for a selected period and generally does not include a cash-value component. Whole life insurance usually costs more because it is designed for lifelong coverage and may include cash value. Actual premiums depend on the applicant, insurer, policy amount, and policy design.
Does whole life insurance always build cash value?
Whole life policies generally include a cash-value component, but the amount and growth depend on the contract. Fees, loans, withdrawals, missed premiums, and surrender can affect the policy. Read the guaranteed and non-guaranteed values carefully.
Can I get life insurance if I have a medical condition?
Possibly. Insurers evaluate health conditions differently. A medical condition may affect approval, price, coverage amount, or underwriting requirements. Answer health questions accurately and compare policies through licensed professionals or authorized insurers.
Do all life insurance applications require a medical exam?
No. Some applications use medical questions, electronic records, or other underwriting methods instead of a traditional exam. However, an exam may be requested based on age, health information, coverage amount, and the insurer’s rules.
Who should be the beneficiary?
Many people name a spouse, children, or another person who depends on them financially. Some situations involve a trust or organization. Beneficiary decisions can have legal and tax implications, so consider professional guidance when the situation is complex.
Should I buy term and whole life insurance together?
Some households consider combining policy types when they have both temporary and permanent financial needs. This is not automatically suitable. Compare the total premiums, goals, affordability, and policy terms before making a decision.
How often should I review my life insurance?
Review it after major life events and periodically as your income, debts, dependents, savings, and goals change. A policy review can help identify outdated beneficiaries, insufficient coverage, or premiums that no longer fit your budget.
Final Takeaway
The right amount of life insurance is the amount that helps address your household’s realistic financial gap without creating an unaffordable premium. Start by adding debts, income replacement, future goals, and final expenses. Then subtract savings and existing coverage.
Term life insurance may be useful for temporary needs and a limited budget. Whole life insurance may be considered when lifelong coverage and cash-value features are important. The best choice depends on your circumstances and the details of the contract, not on a single rule or sales illustration.
Compare similar policies, check the insurer’s authorization and financial information, read the contract carefully, and seek qualified professional advice when your situation is complicated.
Disclaimer
This article is for general educational and informational purposes only. It is not financial, legal, tax, insurance, or investment advice, and it does not recommend any specific insurer, policy, product, coverage amount, or purchase. Insurance availability, premiums, underwriting decisions, exclusions, benefits, and policy terms vary by insurer, state, applicant, and policy. Rates and requirements may change. Review official policy documents and consult a properly licensed insurance professional before making a decision.